

Acorns Early: Kids Money App
by Acorns
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
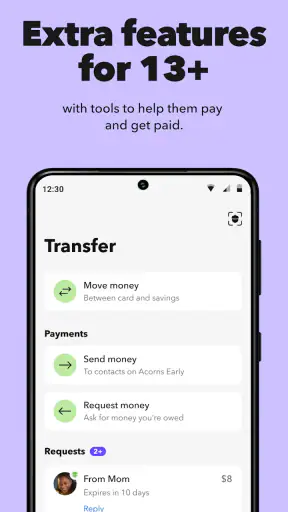
 Analysis by Getfullapps
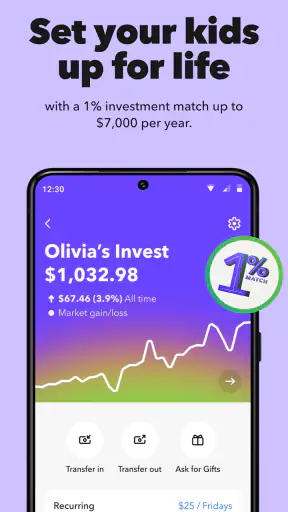
I approached Acorns Early: Kids Money App as a parent-focused finance app rather than as a miniature banking game. Its purpose is to help families introduce investing and money habits through a plan aimed at children and teenagers. That focus matters: this is not simply an app for checking a balance or tracking pocket money. It is designed around the longer-term idea of building financial awareness early, with Acorns handling the investing side.
My first impression was that the app makes a complicated subject feel less intimidating. Investing can sound too advanced for a child, while parents may not want to turn every conversation about money into a lecture. The appeal here is the chance to make financial planning part of an everyday family routine. Still, I would not treat it as a complete financial education course or as a replacement for a parent’s judgment. Its usefulness depends heavily on how adults introduce it and how clearly they explain what saving, investing, risk, and time actually mean.
How Acorns Early fits into a family money routine
Acorns is the developer behind this free finance app, which is available for Everyone and runs on Android devices using version 7.0 or later. It was released on November 8, 2024, and the current version is 9.7.0. Those details make it a relatively recent option for families looking for a child- and teen-oriented investing experience rather than a general-purpose adult finance dashboard.
The store summary presents the app as a way to build a child’s or teenager’s financial wellness with a smart investing plan. In practical terms, I see its role as a bridge between a parent’s financial decisions and a young person’s developing understanding of money. The child is not expected to become an investor overnight. Instead, the app gives the family a reason to discuss where money goes, why long-term planning matters, and how small decisions can connect with future goals.
That makes the app most interesting for parents who want a structured starting point. A spreadsheet can record allowances, and a standard savings account can hold money, but neither automatically creates a shared conversation about investing. Acorns Early is aimed at that missing middle: introducing the topic in a way that feels connected to a child’s future rather than to abstract market terminology.
I would be careful, however, about reading “smart investing plan” as a promise of guaranteed growth or personalized financial success. Investing always involves choices and uncertainty. The app may help organize the experience, but it cannot remove market risk or replace an adult’s responsibility to understand what is being set up. That distinction is especially important when the account or plan concerns a minor.
The cost question is refreshingly simple, but value still needs context
The app itself is listed as free, so installing it does not require an upfront purchase. That is useful for families who want to inspect the experience before committing money to a financial plan. It also lowers the barrier for a parent who is unsure whether a child will engage with the idea or whether the family’s routines are ready for it.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Free access should not be confused with every financial outcome being free. The app’s purpose involves investing, and the value of an investment plan cannot be judged in the same way as a paid game or a premium productivity tool. I would separate three questions before using it: whether the app can be installed without payment, whether setting up an investing arrangement involves any costs or conditions, and whether the chosen investments suit the family. The listed price answers only the first question.
That is an important practical checkpoint. A parent should read the current terms, understand any account requirements, and identify how money moves into and out of the plan before treating the app as a long-term solution. I would not make a decision based only on the word “free.” For a finance product, the real value comes from the clarity of the arrangement and the usefulness of the habits it helps create.
There is also a psychological benefit to the free entry point. Families can begin with a conversation and an inspection of the workflow rather than feeling pressured to pay before understanding the product. My advice would be to use that opportunity deliberately: explore the app together, ask the child what they think the plan is doing, and make sure both parent and child understand which decisions belong to the adult.
What the app can add beyond ordinary pocket-money tracking
The strongest value is educational rather than decorative. A child who only receives occasional cash may learn that money can be spent or saved, but an investing plan introduces a third idea: money can be placed toward a longer-term objective. That shift can help parents explain patience, delayed gratification, and the difference between a short-term purchase and a future goal.
One realistic use case would be a teenager who receives money for chores or special occasions. Instead of treating every payment as spending money, the parent could use the app as the starting point for dividing the conversation into immediate needs, near-term savings, and longer-term investing. The app does not need to turn that into a complicated lesson. Its presence can simply make the plan visible enough for the family to revisit it regularly.
A less obvious strength is that it can help parents move from one-time talks to repeated check-ins. Financial education often fails when it happens only once, usually after a child has made a purchase a parent dislikes. A recurring review of the plan creates a calmer setting. The parent can ask what the child remembers, what goal matters now, and whether the original plan still makes sense.
Another useful workflow is to connect the app with a specific goal without promising a specific result. A family might discuss future education, a first car, or general financial independence, then use the goal as a reason to learn about time and uncertainty. The goal should guide the conversation, not become a guarantee. I would avoid telling a child that investing will definitely pay for something later, because that creates the wrong lesson even if the app makes planning feel straightforward.
The app may also be valuable for parents who feel uncomfortable teaching investing because they do not consider themselves experts. Having a dedicated child- and teen-oriented product gives them a concrete object to discuss instead of trying to explain every financial concept from memory. That does not eliminate the need to learn, but it can make the first conversation easier and less formal.
Where the experience needs adult supervision
The biggest trade-off is that a child-friendly presentation can make investing seem safer or simpler than it really is. I would use plain language with a child: the money is being put to work for the future, its value can change, and waiting longer does not guarantee a particular outcome. Those points are more important than making the experience sound exciting.
Parents should also decide how much control the child receives over the routine. A younger child may benefit from seeing progress and hearing explanations without making financial decisions. A teenager may be ready to ask more detailed questions, compare goals, or help choose how to divide money. The right level of involvement will vary, and the app should support a family conversation rather than dictate one.
There is a second trade-off between convenience and understanding. A guided investing plan can reduce the burden of making every decision manually, which is helpful for busy parents. At the same time, convenience can discourage users from learning what the plan actually does. I would treat any automated or simplified process as a reason to review the details, not as a reason to skip them.
Compared with a regular savings account, this app is more appropriate when the family wants to discuss long-term investing rather than merely protect money for a nearby purchase. A savings account is usually easier to explain for an emergency fund, a birthday gift, or a goal that is only a short distance away. Acorns Early becomes more relevant when the family is comfortable discussing a longer horizon and the possibility that value can move up or down.
Compared with a simple allowance tracker, the app offers a more ambitious financial lesson, but it may be less suitable for teaching day-to-day spending discipline on its own. A tracker can show where pocket money disappears, while an investing plan focuses attention on the future. I would not expect one tool to do both jobs perfectly. Some families may get better results by using a basic spending routine alongside this app rather than asking it to manage every part of a child’s money education.
Compared with opening an adult-oriented investment app and explaining it to a child, Acorns Early has a clearer family angle. That is a meaningful advantage for parents who want the experience to feel age-appropriate. The trade-off is that adults who already have a detailed investing system may find a child-focused product less flexible than the tools they normally use. In that situation, the app’s value depends on whether its family framing improves communication enough to justify maintaining another financial workflow.
Small habits that make the plan more useful
I would begin with a modest, understandable routine rather than presenting the app as a major financial project. For example, set aside a short monthly conversation in which the child explains the goal in their own words. The parent can then discuss what changed, what did not change, and why investing should not be judged by a single moment. This turns the app into a teaching aid instead of a screen the child is expected to check constantly.
A second tip is to separate contributions from performance when talking with children. If the value changes, explain that the family’s deposits and the investment’s movement are different things. That distinction helps prevent a child from believing that a lower balance means they personally failed or that a higher balance came only from making a good choice. It is a simple but important lesson that many generic money apps never address.
A third useful approach is to let the child connect the plan with a written goal while keeping expectations realistic. The goal can be a sentence in a notebook or a family discussion, not necessarily a complicated target inside the app. The point is to make the reason for investing visible. If the goal changes, that is also educational: families can explain that financial plans need review as circumstances change.
I would also avoid turning the app into a reward system based on market movement. Praising a child because the value rose, or criticizing the plan because it fell, teaches short-term checking rather than long-term thinking. The better reward is understanding: can the child explain why the money is invested, why the value may fluctuate, and why adults remain responsible for the decisions?
Who is likely to get the most from it
This app is a strong fit for parents who want to introduce investing before a child becomes financially independent. It is especially suitable when the family already has a habit of discussing money and wants a specific, child-oriented way to extend that conversation. The free installation makes it easier to investigate without paying at the door, although I would still review all financial terms before committing funds.
It may also suit families with teenagers who are beginning to ask practical questions about work, saving, college, transportation, or adult life. A teenager may not need a lecture about compound growth, but they may respond well to seeing how a long-term plan differs from spending money today. The app can provide a shared reference point for those conversations.
Parents who are new to investing may appreciate the guided focus, provided they are willing to learn alongside their child. I would not recommend handing the app over and assuming the product will teach everything automatically. The best results are likely to come when the adult uses it as a prompt, explains unfamiliar terms, and checks that the child understands the difference between a plan and a promise.
On the other hand, I would skip it if the family’s immediate priority is budgeting daily expenses, tracking chores, or teaching basic spending limits. A dedicated allowance or budgeting tool may be better for those jobs. I would also hesitate if the parent is looking for guaranteed returns, instant access to money, or a completely hands-off financial decision. Those expectations do not match the nature of investing.
It may be less appealing to experienced investors who already have a well-organized family strategy and do not need a separate child-focused layer. In that case, the main reason to use it would be communication with the child, not advanced control. If the family cannot explain the plan in simple terms, adding another app will not solve the underlying problem.
What the adoption numbers suggest, and what they do not prove
The app has an average rating of 4.5 from around 3.2 thousand ratings, with 533 written reviews and more than 100 thousand installs. That level of activity suggests that other users are finding enough value to try and rate it, and the rating is encouraging for a relatively recent finance app. I see it as a positive signal when deciding whether the app is worth exploring.
Even so, ratings cannot tell me whether the product fits a particular family’s financial situation. A parent should still inspect the experience personally, read the important account information, and decide whether the investing approach is understandable. A high average rating is useful context, not a substitute for due diligence.
My verdict for families deciding whether to try it
I recommend Acorns Early as a starting point for parents who want to make long-term money conversations more concrete. Its free listing removes an initial installation cost, its child- and teen-focused purpose gives it a clear identity, and its connection to investing makes it more substantial than a simple spending tracker. The most valuable outcome is not a constantly changing balance; it is a child gradually learning that money can be planned, discussed, and assigned to different time horizons.
My recommendation comes with a firm condition: adults should stay involved. Read the financial details, understand the arrangement, explain risk honestly, and decide how much responsibility is appropriate for the child’s age. Use the app during calm, occasional conversations rather than presenting it as a scoreboard. That approach protects the educational value from being overwhelmed by short-term market reactions.
The best reason to choose this app is not that it makes investing effortless; it is that it gives a family a practical reason to talk about investing together. If that is the gap in your current routine, the free download is worth exploring. If you mainly need allowance tracking, everyday budgeting, or guaranteed access to saved cash, a more focused alternative will probably serve you better. For the right family, though, Acorns Early offers a sensible first step toward making financial planning part of growing up.
In my experience, that makes it a thoughtful finance app rather than a complete solution. It will not replace parental guidance, careful reading, or broader money lessons, but it can give those lessons a useful home. For families ready to treat it as a conversation tool and a long-term planning aid, I would choose it over a generic adult investing app pushed onto a child without adaptation.
Pros
- Teaches saving habits through simple, child-friendly activities.
- Parents can set goals that make allowance management more engaging.
- Designed to introduce money concepts at an age-appropriate pace.
- Encourages conversations between parents and children about finances.
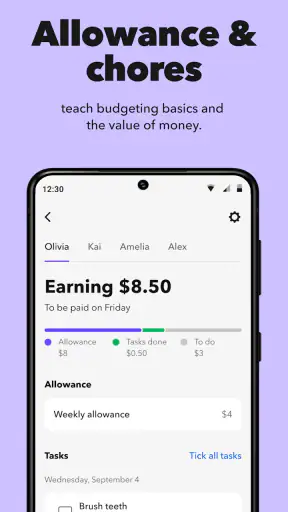
- Can help children connect chores with earning and responsibility.
Cons
- Some features may require a paid Acorns subscription or eligible account.
- Availability and functionality can vary by country and account type.
- Children may need regular parental guidance to understand the lessons.
- Digital rewards may not replace practical experience with physical money.
- Parents should review privacy and data-sharing settings before use.
FAQs for Acorns Early: Kids Money App
What is Acorns Early: Kids Money App, and who is it designed for?
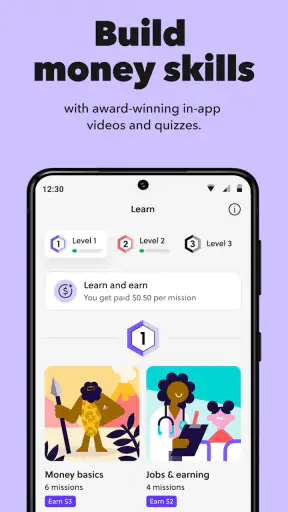
Acorns Early: Kids Money App is a family-focused financial education and money management tool designed to help parents introduce children to saving, spending, and earning concepts. Parents can typically use it to create a supervised financial experience, while children learn through age-appropriate activities and practical money habits. It is best suited to families who want guidance and parental oversight rather than unrestricted access to financial tools.
Is Acorns Early: Kids Money App safe for children to use?
The app is designed with parental involvement in mind, so children do not simply receive an unsupervised financial account. Parents generally manage permissions, monitor activity, and decide how the app fits their family’s rules. However, parents should still review privacy settings, connected accounts, notifications, and any available card controls before allowing use. Children should also be taught not to share passwords, PINs, or personal information.
Does Acorns Early require a subscription or additional fees?
Acorns Early may be available as part of an Acorns family plan or another paid membership, depending on the current offering and the parent’s location. Pricing, included features, card availability, and possible transaction-related charges can change, so it is important to check the official pricing page before downloading or subscribing. Parents should also confirm whether the child features are included or require an upgrade to an existing Acorns account.
Can children earn, save, and spend money through the app?
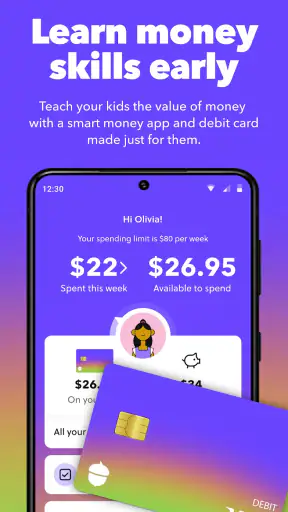
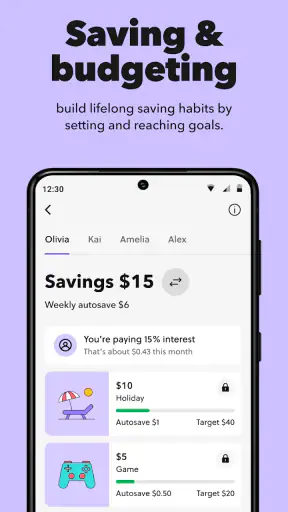
The app is intended to support real-world money lessons, which may include receiving money, setting savings goals, tracking balances, and spending with parental controls when an eligible payment card or account is available. Exact capabilities depend on the child’s age, the parent’s account, regional availability, and the current Acorns plan. Parents should review spending limits and approval settings so the experience matches the child’s maturity and family budget.
What should parents check before downloading Acorns Early?
Before downloading Acorns Early, parents should verify device compatibility, supported countries, current pricing, age requirements, and the financial features available in their region. It is also worth reading the privacy policy and terms, checking whether identity verification is required, and understanding how deposits, withdrawals, cards, and parental controls work. Families should treat the app as an educational aid, not a replacement for conversations about budgeting, online safety, and responsible spending.

Acorns Early: Kids Money App
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@acornsearly.com, visit https://www.acorns.com/early/, or review their https://www.gohenry.com/us/terms-and-conditions/privacy-policy/.










